What Is an NBFC? Meaning, Full Form & How NBFC Loans Work

When you need a loan, banks are the only option that comes in your mind. But banks are not the only institutions that can provide you a loan. NBFCs, which stand for Non-Banking Financial Companies, can also offer various financial services, which include personal loans, vehicle loans, and business loans. It play an important role in making credit available to individuals and businesses that have different financial needs. But they don’t operate the same way as banks, and understanding the difference between both of them will help the borrower to make an informed decision. So what is a NBFC, how does that work, and what should you know before you apply for an NBFC loan? Let’s understand everything.
What Is the Full Form of NBFC?
NBFC means Non-Banking Financial Company.
NBFC is a financial company that provides various services such as loans, advances, and certain investments. Non-Banking Financial Company helps you the individuals and businesses to access the credit for their needs, including personal expenses, vehicle purchases, and business funds.
Non-Banking Financial Company in India are regulated by the Reserve bank of India, which is subject to a regulatory framework. So, their rules and permitted activities differ from banks.
What Is an NBFC?
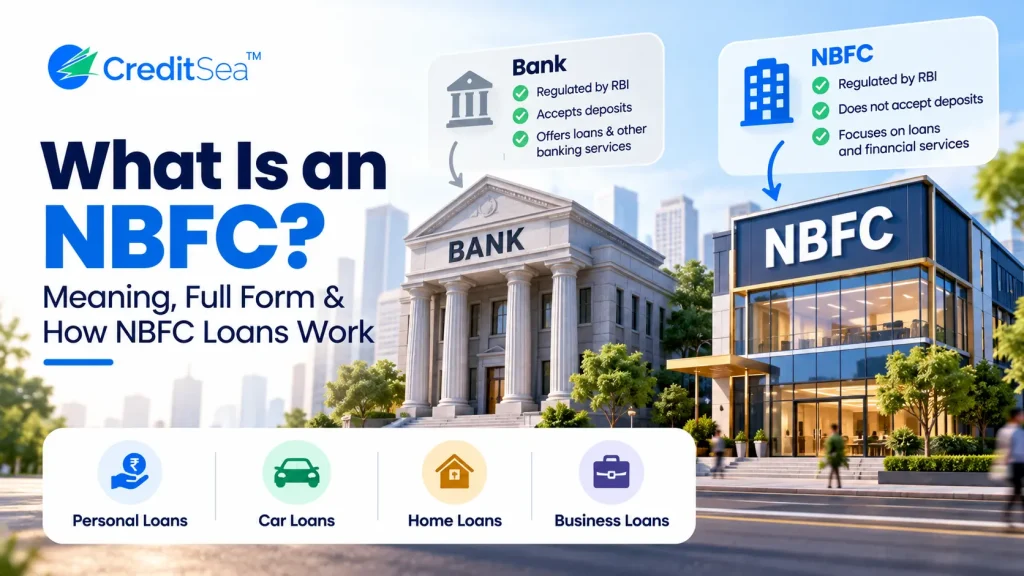
NBFC or Non-Banking Financial Company means a company that is engaged in the business of financial services but is not a bank.
For example, if someone needs money urgently for an unexpected expense, a business requirement, or any situation, they can apply for a loan from an Non-Banking Financial Company, depending upon the company and its services. NBFCs play an important role in India’s financial system by offering credit during financial needs. They can provide loans through online applications as well as other channels, depending upon how a company operates that can differ for different companies. So, it is very important to understand that NBFCs are not the same as banks. Although both exist to provide us loan, but NBFCs generally cannot accept demand deposit or issue checks drawn on themselves, just like banks, and their depositors don’t receive the same DICGC deposit insurance protection that only applies to bank deposits.
How Does an NBFC Work?
NBFC provides the financial services by lending money and carrying out the financial activities that are permitted. But when it comes to giving loans, the basic process involves assessing a borrower’s application and deciding whether this loan can be offered.
- Loan application: The borrower starts with filling out the loan application form with all the details that it is asked for.
- Eligibility criteria: Each one has its own eligibility criteria, and they need to check the details of the borrower whether you can repay the loan or not.
- Loan offer: If the borrower’s eligibility criteria has been fulfilled, he or she will be provided with a loan offer that contains all the important details of the loan, like the total loan amount, interest rate, repayment period, and the other applicable charges.
- Agreement and verification: After you receive the loan offer, the borrower will have to review the terms and conditions and complete the required verification and documentation.
- Disbursement: Once the agreement and verification process is completed, the amount will be credited to your account, and this is known as disbursement. The exact process for this might differ depending upon the type of NBFC it is.
The exact process may differ depending on the type of Non-Banking Financial Company, the type of loan and the profile of the borrower. Please be advised that your application submission does not guaranty approval and disbursement.
Types of Loans offered by NBFCs:
It provide different kinds of loans which differ based on the business model and the permissions applicable to them. Loans are classified as follows:
- Personal loans: These are kind of unsecured loans and they can be used for personal needs.
- Vehicle Loans: These are loans that help you buy vehicles like cars, two-wheelers and other commercial vehicles.
- Gold loans: In this type of loan, it is provided against gold jewelry, with gold as a collateral.
- Home loans: This is provided mainly by certain housing financial companies that provide a loan for purchasing or constructing a home
- Education loans: Some Non-Banking Financial Companies offer loans for education-related expenses.
Are NBFCs Safe for Borrowers?
NBFCs are a completely established part of India’s finance system; most of them operate under the regulatory supervision of the Reserve bank of India. So, the borrowers should not assume that every loan company or app that claims to be an Non-Banking Financial Company is genuine. Before you apply for the loan, there are many factors that you should check, which include
- Verify the lender: First verify whether the NBFC is registered with the RBI or not. You can refer to the official website of RBI’s information and lists.
- Check the actual lender: If you have applied through a loan app or a digital platform, first identify who the lender is, which is the bank or Non-Banking Financial Company that will provide you the loan.
- Review the key facts statement carefully: Go through the key facts statement carefully; it mentions all the details of the loan, so stay informed before you accept the loan.
- Keep your personal information safe: Beware of apps that ask for your personal details and access to your contacts, photos and other sensitive information
RBI registration does not mean every loan will be right for you. You should check whether the lender is reputable and whether you will be able to pay the loan back before taking out a loan.
Must Read – RBI Loan Approved in 1 Minute: Get Money in Minutes, Not Days
Frequently Asked Questions
What is the full form of NBFC?
NBFC Stands For Non Banking Financial Companies. These are non banking financial companies that provide financial services such as loans and advances, but they don’t operate as banks.
Are NBFCs regulated by the RBI?
Yes, NBFCs working fall under the RBI regulatory frameworks, which are regulated by the Reserve Bank of India. The applicable requirements completely depend on the entity and its activities.
What is the difference between an NBFC and a bank?
Both banks and NBFCs provide loans. But they are different in the kind of services they provide, such as demand accounts and check facilities that NBFCs don’t provide.
Can I get a personal loan from an NBFC?
Yes, many NBFCs offer a personal loan. This is subject to satisfying the lender’s eligibility criteria. This could be your income, debts and credit history.
Are bank loans cheaper than loans from NBFCs?
This is not important, interest rates and other fees will vary from lender and their loan products. Before you choose a loan, compare APR, processing fee and repayment amount.
Can NBFCs accept deposits like banks?
NBFCs generally don’t accept demand deposits. Only the Non-Banking Financial Companies that are specifically permitted by the RBI might accept permitted public deposits.
Conclusion
NBFCs are an important part of India’s financial system, offering loans and other financial services to individuals and businesses. They are providing another source of credit other than traditional banks, with the loan options that vary according to the lender and borrower’s need.
So, choosing an Non-Banking Financial Company loan involves checking whether you qualify and understanding the interest rate, total borrowing cost, and repayment terms that will help you to make an informed decision. Before you apply, compare your options carefully and choose a loan that fits your requirements, rather than putting a financial burden on you to repay it from the bank.